Have Questions? Call Us For Help: 508-690-0012

Can a Special Needs Trust Pay Rent? SSI Housing Rules Explained for 2026

Housing is the largest expense in most beneficiaries’ lives, and “can the trust pay the rent?” is the question I hear most from new trustees. The answer is yes. But there is a Social Security rule that trustees need to understand first, because it changes the math.

The short answer

A special needs trust can pay rent, a mortgage, property taxes, and utilities for the beneficiary. Nothing in trust law or Medicaid law prohibits it. The complication comes from the Supplemental Security Income (SSI) program, which treats shelter paid by someone else as income to the beneficiary and reduces the monthly check accordingly. If your family member does not receive SSI, most of this article does not apply.

In-kind support and maintenance

SSI is a needs-based program, so Social Security counts not only cash income but also help with basic needs. When someone other than the recipient pays for their shelter, Social Security calls it in-kind support and maintenance, or ISM. A trust is “someone else” for this purpose, even though the money is set aside for the beneficiary.

Shelter, for ISM purposes, means rent, mortgage principal and interest, real property taxes, heating fuel, gas, electricity, water, sewer, and garbage removal. It does not include phone, internet, cable, furniture, appliances, repairs, or renter’s insurance. A trust can pay those without any SSI effect.

How much SSI is reduced

The reduction is capped. Under the rule that applies when the beneficiary lives in their own home or apartment and the trust pays some or all of the shelter costs, the most Social Security can count is one third of the federal benefit rate plus $20. For 2026, the federal benefit rate is $994 a month, so the maximum reduction is $351.33.

That cap is the key to planning. Whether the trust pays $400 or $2,000 a month toward housing, the SSI check drops by no more than $351.33.

If the trust pays less than that amount in a month, Social Security counts the actual value of the help instead, minus a $20 general exclusion.

What changed on September 30, 2024

For decades, food counted as ISM alongside shelter. A trust that paid for groceries or meals triggered the same reduction, and trustees tied themselves in knots avoiding it. Social Security published a final rule removing food from the ISM calculation, effective September 30, 2024. Since then, a trust can pay for groceries, restaurant meals, and meal delivery services with no effect on SSI. Social Security estimated that about 41,000 recipients saw their benefit increase by an average of $132 a month when the rule took effect.

Shelter was not part of that change. Rent and utilities paid by the trust still count.

A worked example

Suppose your son receives the full 2026 SSI benefit of $994 a month and rents an apartment for $1,400. If he pays the rent himself, he has almost nothing left for anything else. If the trust pays the rent, his SSI drops by $351.33 to $642.67, but he keeps the entire $994 he would otherwise have spent on rent. His monthly position improves by more than $1,000. Most trustees in that situation pay the rent, report it, and accept the reduction.

Four ways trustees plan around the rule

1. Pay the shelter cost and accept the reduction

As the example shows, when rent is large, the reduction is a small price. The trustee should simply understand it in advance and report it.

2. Pay everything that is not shelter

Phone, internet, cable, streaming, furniture, cleaning, repairs, renter’s insurance, transportation, clothing, and now food are all outside the rule. A trust that covers all of those may leave the beneficiary enough SSI to pay the rent themselves.

3. Route housing money through an ABLE account

Money the beneficiary spends from their own ABLE account on housing is not ISM, because the beneficiary is paying, not a third party. A trust can contribute to the beneficiary’s ABLE account (up to the $20,000 annual contribution limit in 2026, combined from all sources). The beneficiary then pays rent from the ABLE account. One caution: ABLE funds withdrawn for housing must be spent in the same month they are withdrawn, or they become a countable resource the following month.

4. Have the trust own the home

If the trust owns the house or condo the beneficiary lives in, the beneficiary’s rent-free occupancy is generally not ISM, though property taxes, insurance, and utilities the trust pays may still be counted. This is a larger planning step and worth an attorney’s review, but for families with a home to leave, it is often the best long-term answer.

Report it

Whatever the trustee decides, shelter paid by the trust must be reported to Social Security. Unreported ISM shows up later as an overpayment, and Social Security will collect it from future checks. A short letter to the local office, kept in the trust file, is enough.

Two things trustees should never do

  • Give the beneficiary cash for rent. Cash from the trust to the beneficiary is unearned income, counted dollar for dollar after a $20 exclusion. That is far worse than the capped ISM reduction.
  • Skip the trust and have a parent pay directly. The ISM rule applies to any third party. A parent paying rent triggers the same reduction as the trust paying it, without the record-keeping and protection the trust provides.

When housing decisions get complicated

Group homes, shared apartments with roommates, Section 8 vouchers, and family-owned homes each have their own wrinkles. If you are a trustee facing one of those, book a free consultation and we will walk through it. If you do not yet have a trust to hold the money in the first place, our attorney-drafted Will and Special Needs Trust package is $299.

Education is always free. That is the reason the nonprofit exists.

This article provides general legal information, not legal advice. SSI figures are for 2026 and change each January. Questions? Email tom@specialneedstrustsonline.com or call 508-690-0012.
Pooled Special Needs Trust vs. Individual Trust: Which One Fits Your Family?

Pooled trusts are mentioned more often every year, usually by a hospital social worker, a settlement attorney, or a Medicaid caseworker. They are a real option and, for some families, the right one. But the trade-offs are rarely explained before the joinder agreement is signed.

This article compares a pooled special needs trust with an individual trust so you can decide which one fits your family, and know what to ask before you commit either way.

What a pooled special needs trust is

A pooled trust is a special needs trust established and managed by a nonprofit organization. Federal Medicaid law recognizes it specifically. Each beneficiary has a separate sub-account for accounting purposes, but the money of all beneficiaries is pooled for investment, and the nonprofit serves as trustee for everyone.

You do not draft your own trust document. Instead, you sign a joinder agreement that enrolls your family member in the nonprofit’s master trust. Pooled trusts can accept the beneficiary’s own money (a first-party sub-account) or money from parents, grandparents, and others (a third-party sub-account).

What an individual special needs trust is

An individual trust is a document drafted for one beneficiary. A trustee you choose, whether a family member, an independent professional trustee, or a bank, manages it under the terms you set. There are two kinds:

  • A third-party trust holds money from family and friends. It has no Medicaid payback, and the remainder goes to whoever the trust names.
  • A first-party trust holds the beneficiary’s own money, such as a settlement or an inheritance left directly. It must repay Medicaid from what remains at the beneficiary’s death.

Both kinds protect SSI and Medicaid eligibility, and so do their pooled counterparts. The difference between pooled and individual is not whether benefits are protected. It is cost, control, and what happens at the end.

Cost

Pooled trusts charge an enrollment fee, an annual administrative fee, and often a fee per disbursement. Those fees vary widely, so ask for the full schedule in writing. The fees pay for professional administration, which has real value, but on a small account they can be a meaningful percentage every year.

An individual trust has a one-time drafting cost. Our attorney-drafted Third-Party Special Needs Trust and First-Party Special Needs Trust are $299 each; private firms typically charge $3,000 or more. After that, a family trustee usually serves without a fee. If you hire an independent trustee, expect an hourly rate or roughly one percent of the trust per year.

Control and speed

With a pooled trust, the nonprofit decides which requests to approve. Most are reasonable and experienced, but the decision goes through their process, and it can take days or weeks. If your daughter needs a new wheelchair cushion this week, that delay matters.

With an individual trust, the trustee you chose can decide the same day, and the trust document can give specific instructions about the beneficiary’s lifestyle, housing, and priorities. That flexibility is the main reason most parents who have a willing trustee choose their own trust.

What happens to the money at the end

This is the difference families are least often told about.

When the beneficiary of a first-party pooled sub-account dies, federal law allows the nonprofit to retain some or all of what remains for the benefit of other beneficiaries in the pool. Whatever the nonprofit does not keep must go to repay Medicaid. The family typically receives nothing. Policies vary by nonprofit; some keep everything, some keep a percentage, so ask.

With a third-party pooled sub-account, there is no Medicaid payback, but the nonprofit may still retain a share of the remainder under its joinder agreement.

With an individual third-party trust, there is no payback and no retention. The remainder goes to the people you name, often siblings or a charity you care about.

When a pooled trust is the right choice

  • There is no family member or independent trustee available to serve, and the amount is too small for a bank or trust company to accept.
  • The beneficiary is over 65 and needs a first-party trust. Federal law limits individual first-party trusts to beneficiaries under 65, and a pooled trust may be the only option, though some states penalize transfers to a pooled trust after 65. Check your state’s rule.
  • A settlement is small and needs to be protected quickly, without setting up separate trust administration.
  • The family wants professional administration and accepts the fees and the retention policy.

When your own trust is the better fit

  • A parent, sibling, or independent trustee is willing to serve.
  • The money comes from family (third-party), which means no payback and a remainder you control.
  • You want the trustee to respond quickly and to follow instructions specific to your child.
  • The trust will eventually hold a larger amount, such as life insurance or a share of your estate, where annual pooled fees add up.

Questions to ask a pooled trust before you join

  1. What are the enrollment fee, the annual fee, and any per-transaction fees?
  2. What is your policy on retaining funds at the beneficiary’s death, and is it in the joinder agreement?
  3. How long does a typical disbursement request take?
  4. Can a family member be named as an advisor or advocate on the account?
  5. What happens to the sub-account if the nonprofit closes or merges?

You can use both

Some families use a pooled trust for a beneficiary’s own funds, such as a small settlement, and an individual third-party trust for what the parents will leave later. Nothing prevents that, and it often gives the best of each.

If you are weighing the two, book a free consultation and we will walk through the five questions with you. Education is always free. That is the reason the nonprofit exists.

This article provides general legal information, not legal advice. Pooled trust terms and state Medicaid rules vary. Questions? Email tom@specialneedstrustsonline.com or call 508-690-0012.

How Grandparents Can Leave Money to a Grandchild With a Disability Without Ending SSI or Medicaid

A grandparent updates a will and names every grandchild equally. It feels fair. For a grandchild who receives SSI or Medicaid, that equal share can be the most expensive gift they ever receive.

This is one of the most common problems I see in consultations, and it is almost always a surprise to the family. The grandparent meant well. The attorney who drafted the will may never have been told that one grandchild has a disability. The money arrives, benefits stop, and the family spends months trying to undo it.

This article explains why direct gifts cause the problem, what a third-party special needs trust does about it, and the exact instructions to give a grandparent and their attorney.

Why a direct inheritance ends benefits

Supplemental Security Income (SSI) has a resource limit of $2,000 for an individual. In most states, Medicaid eligibility for an adult with a disability is tied to SSI or uses the same limit. Resources are counted on the first day of each month. If your son or daughter has more than $2,000 in countable assets on that day, SSI stops for the month, and Medicaid can stop with it.

An inheritance paid directly to your child is a countable resource the moment they have the legal right to it. So is a life insurance payout, a payable-on-death bank account, or a share of a retirement account where your child is the named beneficiary. The size of the gift does not matter once it crosses $2,000.

The damage goes beyond the monthly check. In many states, Medicaid is the door to waiver services: day programs, personal care, supported employment, and residential support. Losing eligibility, even briefly, can mean losing a place in a program with a waiting list.

What a third-party special needs trust does

A third-party special needs trust is a trust funded with money that belongs to someone other than the beneficiary. Parents, grandparents, aunts, uncles, and family friends can all give to it, during life or at death. A trustee holds the money and spends it for the benefit of your child on things that public benefits do not cover: therapies, travel, a phone, a computer, clothing, recreation, education, and much more.

Because the beneficiary does not own the money and cannot demand it, the trust does not count toward the $2,000 limit. SSI and Medicaid continue.

Two features make the third-party trust the right vehicle for grandparent gifts specifically:

  • No Medicaid payback. When the beneficiary dies, whatever remains in a third-party trust goes to the people the person who created the trust chose, often siblings or a charity. That is different from a first-party trust, which must repay Medicaid first.
  • One destination for everyone. Once the trust exists, every relative can name it. Grandparents, godparents, and friends do not each need their own trust. They only need the trust’s name.

The instructions to give a grandparent

Once your third-party trust is signed, the message to grandparents is short. Here is the language I suggest:

“Please do not leave anything directly to [name]. Instead, leave [name]’s share to the [Family Name] Supplemental Needs Trust dated [date]. Your attorney can add that to your will or trust in a few minutes. The same applies to life insurance and any account with a beneficiary form.”

Give them a copy of the first page and the signature page of the trust so their attorney can confirm the name and date. They do not need the whole document.

Gifts during life work the same way

The same rule applies to birthday and holiday checks. A $500 check written to your adult child is income in the month received and a resource the next month if unspent. A $500 check written to the trust is neither. If grandparents like to give cash, ask them to write it to the trust, or to an ABLE account, which allows up to $20,000 in contributions per year in 2026 from all sources combined without affecting SSI.

What if the money has already been left directly?

If a grandparent has already passed away and the will names your child directly, do not spend the money before you get advice. Two tools may still protect it:

  • A first-party special needs trust can hold the beneficiary’s own money, including an inheritance, and preserve eligibility. It requires a Medicaid payback at the end, but it keeps benefits in place now.
  • An ABLE account can absorb up to the annual contribution limit, and the first $100,000 in an ABLE account is excluded from the SSI resource limit.

Timing matters. Contact us or your attorney before the estate distributes the funds.

A conversation worth having this fall

Many families see grandparents over the holidays. It is a natural time to have this conversation, and it is easier when the trust already exists and you can hand over a name and a date. Our Will and Third-Party Special Needs Trust package is $299 and is drafted by a disability-law attorney. Private firms typically charge $3,000 or more.

If you are not sure which trust fits your situation, book a free consultation. Education is always free. That is the reason the nonprofit exists.

This article provides general legal information, not legal advice. Rules vary by state. Questions? Email tom@specialneedstrustsonline.com or call 508-690-0012.

How to Find an Independent Trustee for a Special Needs Trust

When I meet with families about special needs trusts, the question that stops them is rarely about the documents. It is about the person. Who will manage this trust when we are gone? Some families have an obvious answer: a sibling, an aunt, a trusted friend. Many do not. And when families start looking at banks and trust companies, they find high fees and minimum balances that put a corporate trustee out of reach for an ordinary trust.

There is a middle path that most families have never heard of: the independent trustee.

What an independent trustee is

An independent trustee is an individual professional who administers trusts as their occupation. They are not employees of a bank or a trust company. They run their own small practices, which keeps overhead low, and they usually charge either an hourly rate or a yearly fee of around one percent of the trust. Corporate trustees often charge more than that and may decline trusts below a minimum balance entirely.

The lower fee is not the only advantage. An independent trustee has a small client list, so the person who knows your son or daughter is the same person who answers the phone. For a special needs trust, where the trustee’s decisions touch SSI, Medicaid, housing, and daily quality of life, that continuity matters as much as the cost.

Where to find one: a national directory

Until recently, finding an independent trustee meant asking around and hoping. Now there is a national resource. The Independent Trustee Alliance directory lets you search by state and filter for trustees who handle special needs trusts. ITA certified trustees must have years of trustee experience, ongoing continuing education, professional references, and agree to a code of ethics. A listing is not a guarantee, but it is a real starting point that did not exist for earlier generations of families.

A second place to look is the National Guardianship Association’s Find a Guardian directory, which lists individual professional fiduciaries across the country, many of whom also serve as trustees.

We have added a permanent page to our site with both listings and the questions to ask before you hire anyone: Find an Independent Trustee. You will find it in our Resources menu from now on.

How to interview a trustee candidate

Treat this like hiring for the most important job in your child’s future, because it is. Ask what they charge and when. Ask how many special needs trusts they administer and how they stay current on SSI and Medicaid rules. Ask about their succession plan: what happens to your trust if something happens to them? Ask whether they carry errors and omissions insurance. And ask whether a family member can serve alongside them as co-trustee or trust advisor, which lets your family keep a voice while the professional handles the rules.

One note of caution that applies to any directory: a listing is a starting point, not an endorsement, and that includes the directories we link to. Interview more than one candidate, check references, and make sure the fee arrangement is in writing.

You do not have to decide alone

Our mission is to give families free legal educational information so you can make informed decisions, whether you use our low-cost documents, hire your own lawyer, or both. If you want to talk through your trustee decision, the consultation is free. Education is always free. Email tom@specialneedstrustsonline.com or call 508-690-0012.

Will Medicaid Take What’s Left in Your Child’s Special Needs Trust?

Ask a room full of parents what stops them from setting up a special needs trust, and eventually someone will say it out loud:

“I’ve heard the state takes it all back when he dies. So what’s the point?”

It is the most common reason families walk away from a trust, and for most of them it is simply not true.

The confusion comes from the fact that there are two different kinds of special needs trust, both are called “special needs trusts,” and only one of them has a Medicaid payback. Which one you are dealing with comes down to a single question.

Whose money is it?

That is the whole test. It does not matter who set the trust up or whose name is on it. What matters is whose money went in.

Third-party trust First-party trust
Funded with someone else’s money: parents, grandparents, an aunt, a life insurance policy. Funded with the beneficiary’s own money: a lawsuit settlement, back benefits, an inheritance that landed in their name.
No Medicaid payback. Whatever is left goes wherever you said it should go: siblings, grandchildren, a charity. Medicaid payback required by federal law. At death, the state is reimbursed first. Anything left over then passes to your heirs.
Can be created at any time, at any age. Must be established before the beneficiary turns 65.

So here is the answer to the question that stops so many families:

If you are a parent or grandparent planning to leave money to a loved one with a disability, you are creating a third-party trust. There is no Medicaid payback at any point. The money you leave stays in your family.

The payback rule that everyone has heard about is real, but it attaches to the first-party trust, and only because Congress required it in exchange for letting someone shelter their own money and stay on benefits. It is the price of a very good deal, not a punishment. A fuller side-by-side comparison is here →

The mistake that turns one into the other

Now the part that actually costs families money.

A third-party trust only stays a third-party trust if the money goes straight into it and never touches your child’s hands. The moment an inheritance lands in your adult child’s name, even for a day, even by accident, it becomes their money. Their money can only be sheltered in a first-party trust, with the payback.

Here is how that happens in real life, over and over:

  • A grandparent writes a will leaving “$25,000 to each of my grandchildren,” with the best intentions in the world.
  • A parent names their adult child as a beneficiary on a life insurance policy or a retirement account, because that is what the form asks for.
  • A relative dies without a will, and state law hands your child a share automatically.
  • A well-meaning aunt opens a savings account for your child and puts their name on it.

Any one of these can do two things at once. It can push your child over the $2,000 resource limit and knock them off SSI and Medicaid, and it can convert money that could have passed cleanly to the family into money the state gets reimbursed from.

The fix is simple. Nobody leaves money to your child. Everybody leaves money to the trust, and the trust takes care of your child. The same money serves the same purpose with a completely different outcome.

Three things to do this month

  1. Set up the third-party trust first. It has to exist before anyone can name it. Until it does, every relative’s will is pointed at a target that is not there.
  2. Check your beneficiary designations. Life insurance, 401(k), IRA, pension, savings bonds. These pass outside your will. A perfect will cannot save a retirement account that names your child directly. This is the most commonly missed step in special needs planning, and it takes twenty minutes to fix.
  3. Tell the grandparents. Have the conversation, awkward as it is. Give them the exact language: leave the gift to the trust, not to the child. Most families find that relatives are relieved to be told. They were worried about doing the wrong thing and had no idea what the right thing was.

Watch: Special Needs Trusts & Wills Explained

Attorney Tom Sannicandro walks through how the trust and the will work together, why beneficiary designations matter more than most families realize, and what belongs in each document.

What if the money is already in your child’s name?

It happens, and it is not fatal. A first-party special needs trust can still shelter it and protect their benefits. The payback applies, but the alternative is spending the money down to $2,000 and losing years of Medicaid coverage in the meantime. Sheltering it is almost always the better outcome. First-party trusts for adults with disabilities →

An ABLE account can also hold a modest amount of the beneficiary’s own money. Note that ABLE accounts do carry a Medicaid payback, which is another reason the large, long-term money belongs in a third-party trust and the everyday spending money belongs in ABLE.

What it costs

Attorneys typically charge $3,000 to $5,000 for a special needs trust and a coordinated will. We are a 501(c)(3) nonprofit founded by a disability law attorney who is also the father of an adult son with Down syndrome, and a complete personalized trust and will is $189.99. You answer guided questions in plain English and the documents are emailed to you when you finish.

The Letter of Intent and the HIPAA Release are free to anyone, with no purchase.


Create Your Third-Party Special Needs Trust →

Not sure which kind you need? Book a free 10-minute session and we will tell you straight.


This article is general information about how these trusts work, not legal advice about your family’s situation. State Medicaid rules and trust requirements vary. If your situation involves a settlement, an inheritance already received, or a trust that has already been funded, talk with us or with an attorney in your state before you act.

Your Child With a Disability Is Turning 18: The 7 Documents to Have Before the Birthday

The day your child turns 18, you lose the legal right to talk to their doctor, see their school records, and manage their money. Nobody warns you ahead of time.

There is no letter in the mail and no meeting at the school. One morning your son or daughter turns 18, and the pediatrician’s office that has known your family for eighteen years can no longer legally tell you the results of a blood test. The school that has sat across the table from you at every IEP meeting since kindergarten now answers to your child instead of you. The bank will not talk to you. The insurance company will not talk to you.

This surprises almost every family. It should not have to.

The good news is that every one of these doors can be held open. It just has to be done before the birthday, by signing a handful of documents while everyone has time to do it calmly. Below is exactly what changes at 18, what you can do about it, and the order to do it in.

What actually changes the day your child turns 18

Four things happen at once, automatically, with no paperwork and no warning:

  • Medical privacy locks you out. Under HIPAA, your adult child’s health information belongs to them. Doctors, therapists, hospitals, and pharmacies can refuse to speak with you, and in an emergency many will.
  • School records transfer to your child. Under FERPA, the right to see records and consent to services moves from you to the student at 18. If your child is still in high school or in a transition program that runs to age 22, you can be shut out of the IEP process you built.
  • Financial and legal authority ends. You can no longer sign for them, open accounts for them, apply for benefits on their behalf, or make decisions about their money.
  • SSI gets re-decided under adult rules. Social Security performs an age-18 redetermination, re-evaluating disability based on ability to work rather than childhood functioning.

There is another side to that last change, and most families have never heard it:

Your income stops counting at 18. While your child is a minor, Social Security counts a parent’s income and resources against the child. That is why so many families are told their child does not qualify for SSI. The counting stops at 18. A child who was denied SSI because you earned too much may now qualify on their own. If you were turned down before, apply again after the birthday.

Qualifying for SSI also usually opens the door to Medicaid, and Medicaid is often the single largest source of lifetime support your child will ever have. The application is worth the effort.

The fork in the road: guardianship or something lighter?

When families learn what happens at 18, the first word they usually hear is guardianship. It is the traditional answer, and for some families it is the right one. It is not the only one, and it is not the default.

Guardianship is a court proceeding. A judge declares your adult child legally incapacitated and transfers their decision-making rights to you. It costs money, takes months, usually requires a current medical or psychological evaluation, and is difficult to undo. It also removes rights, including in many states the right to vote, to marry, and to sign a contract.

For some people, that level of protection is necessary and appropriate. For many others, it is more than the situation calls for. Courts across the country now ask a harder question first: what is the least restrictive arrangement that actually keeps this person safe?

The lighter alternatives:

  • Supported Decision-Making: your child keeps their legal rights and formally names people they trust to help them understand choices and consequences. It is the fastest-growing alternative in the country.
  • Power of Attorney: your child voluntarily gives you authority over financial and legal matters. It requires that they understand what they are signing, which is a lower bar than most people assume.
  • Health Care Proxy / Advance Directive: names you to make medical decisions if they cannot.
  • Representative Payee: lets you manage their SSI or SSDI payments without any court involvement at all.

The important thing is this: the alternatives are only available while your child can still sign. Once you go to court, that option is largely gone. It is worth doing the lighter documents first and reserving guardianship for the situations that truly require it.

The 7 documents to have before the birthday

1. HIPAA Release (free)

The most valuable piece of paper for the least effort. One page, signed by your child, and doctors can talk to you again. If you do nothing else on this list, do this one. Get the free HIPAA release →

2. Health Care Proxy / Advance Directive

The HIPAA release lets you hear what is happening. The health care proxy lets you decide. If your child cannot make or communicate a medical decision, this document names you. Requirements vary by state, so use a form built for yours. State-specific healthcare directives →

3. Power of Attorney

Covers money, benefits applications, contracts, housing, and the hundred administrative things that come up. Power of Attorney →

4. Power of Attorney for Education

The one families forget until they are locked out of an IEP meeting. If your child is still in school or heading into a transition program, this keeps you at the table. Power of Attorney for Education →

5. Supported Decision-Making Agreement

Formalizes who helps your child think through decisions, without taking away their right to make them. Increasingly recognized by schools, doctors, and banks. Supported Decision-Making →

6. Special Needs Trust (and your own Will)

Here is the trap: your adult child can lose SSI and Medicaid by owning more than $2,000. A well-meaning inheritance from a grandparent, a life insurance payout, or a bequest in your own will can disqualify them from the benefits they depend on.

A third-party special needs trust holds those assets for your child without the assets counting as your child’s. The money can still be spent on their life, including education, therapy, a vehicle, technology, travel, and recreation, but eligibility stays intact. Your will has to be written to point into the trust, which is why the two documents belong together.

Special Needs Trust for parents →  |  Trust + Will together →

7. Letter of Intent (free)

It is not a legal document, but it may be the most important one anyway. This is where you write down everything the legal papers cannot hold: the morning routine, what calms them down, the foods they hate, the cousin they adore, what a good day looks like. Someday someone who is not you will be reading it. Get the free Letter of Intent →

Watch: Turning 18 and 22, the legal and financial changes explained

Attorney Tom Sannicandro walks through what changes at each milestone, the benefit rules that trip families up, and how the documents above fit together.

Short on time? Supported Decision-Making explained in 5 minutes →

When to do what

Timing What to do
12 months beforeDecide the big question: guardianship, or a less restrictive path? Talk to your child’s doctors and teachers. Book a free planning session if you are unsure.
6 months beforeIf you are pursuing guardianship, start now. Evaluations and court schedules make this slower than anyone expects.
3 months beforeSign the HIPAA release, health care proxy, powers of attorney, and any supported decision-making agreement. Give copies to every doctor and to the school.
The birthday monthApply, or re-apply, for SSI under adult rules. Apply to be representative payee. Register to vote. If your child is male, confirm Selective Service registration, since it affects future federal aid.
Within the first yearPut the special needs trust in place, update your own will to fund it, open an ABLE account, and write the Letter of Intent.

One more thing worth knowing about ABLE accounts

As of January 1, 2026, ABLE accounts opened up dramatically. Eligibility now extends to anyone whose disability began before age 46, up from 26. Millions of people, including a large number of veterans, became eligible this year and do not know it.

An ABLE account and a special needs trust are not competitors. The account is for everyday spending your child controls, with a debit card and a yearly contribution cap. The trust is for the large, long-term money, such as an inheritance, a home, or life insurance, and has no cap at all. The strongest plans use both. More on ABLE accounts →

What this usually costs, and what it costs here

The reason so many families arrive at the eighteenth birthday with nothing signed is not that they did not care. A law firm quoted them $3,000 to $5,000 and they put it off for a year, and then another year.

We are a 501(c)(3) nonprofit founded by a disability law attorney who is also the father of an adult son with Down syndrome. A complete personalized special needs trust and will is $189.99. The HIPAA release and the Letter of Intent are free to anyone, with no purchase. Documents are emailed to you as soon as you finish the questions. That price is possible because the nonprofit was created for exactly this purpose.


Start with the free one

If the birthday is coming and you are not sure where to begin, begin with the HIPAA release. It takes a few minutes, it costs nothing, and it is the document families tell us they wished they had the first time they stood in an emergency room and were told they were not allowed to know anything.

Get the Free HIPAA Release →

Or book a free 10-minute planning session and we will tell you honestly which documents your family actually needs, and which ones you can skip.


This article is general information about how the law works at age 18, not legal advice about your family’s situation. Rules for guardianship, powers of attorney, and healthcare directives vary by state. If your situation is complicated, or if you are weighing guardianship, talk with us or with an attorney in your state before you sign anything.

When the clocks change it is a good time to update your special needs trust

Don't Forget To Update Your Special Needs Trust

As we approach the time of year when we move our clocks forward, it’s important to remember that this is also an excellent opportunity to revisit your estate planning documents, including your special needs trust. Updating your special needs trust when the clocks go ahead can help ensure that your loved one with special needs continues to receive the support they need, even after you’re gone. In this blog post, we’ll explore why updating your special needs trust when the clocks go ahead is a smart move.

What Is A Special Needs Trust?

Before we delve into why it’s important to update your special needs trust, let’s first understand what it is. A special needs trust is a legal document that allows you to set aside money and assets for the benefit of a person with special needs. These trusts are designed to help individuals with disabilities maintain eligibility for government benefits while still receiving the additional support they need.

Changes in Laws & Regulations - Update your Special Needs Trust

Laws and regulations regarding government benefits and special needs trusts can change over time. Updating your special needs trust when the clocks go ahead can ensure that it is in compliance with any new laws or regulations that may have been enacted since you last updated it. This will help ensure that your loved one with special needs continues to receive the support they need without any interruptions.

Changes In Your Personal Situation

Your personal situation may change over time, and your special needs trust should reflect those changes. For example, you may have acquired new assets or received an inheritance that you would like to include in the trust. Or, you may have had another child who you want to include in the trust. Updating your special needs trust when the clocks go ahead can help ensure that it reflects your current situation and that it continues to meet the needs of your loved one with special needs.

Changes In Your Your Loved One's Needs

Finally, your loved one’s needs may change over time. Perhaps they require additional medical care or have developed a new interest that requires additional funding. Updating your special needs trust when the clocks go ahead can help ensure that it continues to meet the evolving needs of your loved one with special needs.

Conclusion - The Importance Of Updating Your Special Needs Trust

Updating your special needs trust when the clocks spring forward is not just a prudent action; it’s a proactive measure that can safeguard the ongoing support and well-being of your loved one with special needs, long into the future. As time progresses, various factors such as shifts in laws and regulations, alterations in your personal circumstances, and changes in your loved one’s needs can all impact the efficacy and relevance of your special needs trust. Therefore, it’s imperative to conduct regular reviews and updates to ensure that the trust aligns with your current situation and your loved one’s evolving requirements. If you haven’t revisited your special needs trust in some time, the onset of daylight saving time presents an opportune moment to do so. By taking the initiative to review and potentially revise your trust document now, you can proactively address any outdated provisions, anticipate future challenges, and make necessary adjustments to enhance its effectiveness. Don’t underestimate the importance of this task; by staying proactive and vigilant, you can ensure that your loved one receives the comprehensive support and protection they deserve, both now and in the years to come.

Special Needs Trusts Online Can Help!

I am a Special Needs Trust Attorney and I am here to help. I am the founder of a nonprofit corporation to that provides quality information about resources available to families as well as providing affordable Special Needs Trusts and estate planning for families. I have over 20 years of experience helping families just like yours. Find out more information at SpecialNeedsTrustsOnline.com or click here to set up a free appointment.

Source: specialneedstrustsonline.com

What Is the difference between a “First-Party” Special Needs Trust and a “Third Party” Special Needs Trust ?

First Party Special Needs Trust Vs Third Party Special Needs Trust

Special Needs Trusts (SNTs) are an important tool for individuals with disabilities to ensure their financial security. There are two types of SNTs, commonly designated as first-party and third-party SNTs. It is important to determine which type of SNT you have or need, as this depends upon whose property is funding the trust.
First Party Special Needs Trust Vs Third Party Special Needs Trust​

If the property funding the SNT originates with the SNT beneficiary, then it must be drafted as a first-party SNT

This type of trust is often used when the beneficiary has received a settlement from a lawsuit or inheritance from a family member. On the other hand, if the property funding the SNT always belonged to someone other than the SNT beneficiary, then it must be drafted as a third-party SNT. This type of trust is typically used when someone other than the beneficiary wants to provide funds for their care and support without affecting their eligibility for government benefits such as Medicaid or Supplemental Security Income (SSI).

First Party Special Needs Trust

A first-party special needs trust is a type of trust that is designed to provide financial support for individuals with disabilities without affecting their eligibility for government benefits. This type of trust is typically funded with the disabled individual’s own assets, such as an inheritance or settlement from a lawsuit. The funds in the trust are used to pay for items and services that are not covered by government programs, such as medical care, housing, transportation, education, recreation and other expenses related to the beneficiary’s disability.

First-party special needs trusts can be useful in many situations. For example, if a disabled individual receives an inheritance or settlement but does not have enough income to cover all of his or her living expenses, a first-party special needs trust can be used to supplement the individual’s income while still allowing him or her to remain eligible for government benefits. Additionally, these trusts can help protect assets from being depleted due to medical costs and other expenses associated with the disability. Finally, they can also provide peace of mind knowing that there will be funds available should something happen to the disabled individual’s primary caregiver.

Frequently Asked Questions About First Party Special Needs Trust Vs Third Party Special Needs Trust

The key distinction lies in who funds the trust. A First-Party Special Needs Trust is funded with the disabled individual’s own assets, while a Third-Party Special Needs Trust is funded by assets belonging to someone other than the beneficiary, such as a parent or grandparent.
Generally, to establish a First-Party Special Needs Trust, the individual with a disability must be under the age of 65 and must meet the Social Security Administration’s definition of disability.
Medicaid typically imposes a payback requirement for funds remaining in a First-Party Special Needs Trust upon the beneficiary’s death, while assets in a Third-Party Special Needs Trust may be distributed to other beneficiaries or charities without a payback to Medicaid.
No, a First-Party Special Needs Trust must be established by a parent, grandparent, legal guardian, or the court. It cannot be established by the individual with a disability.
Funds from a Third-Party Special Needs Trust can be used to supplement the beneficiary’s government benefits, pay for medical and dental expenses not covered by insurance, provide for recreational activities, and enhance their quality of life without jeopardizing their eligibility for public assistance programs.

Need Information About Special Needs Trusts?

I am Tom Sannicandro, a Special Needs Trust Attorney and I am here to help. I am the founder of a nonprofit corporation that provides quality information about resources available to families as well as providing affordable Special Needs Trusts and estate planning for families. I have over 20 years of experience helping families just like yours. Find out more information at SpecialNeedsTrustsOnline.com or click here to set up a free appointment.

What to do after you have signed your wills and special needs trust

What to Do After Signing a Will and Special Needs Trust

What to Do After You Have Signed
Your Will and Special Needs Trust

Congratulations on taking a major step toward protecting your family's future. Here is everything you need to do next.

Posted December 30, 2022  ·  By Tom Sannicandro

What To Do After You Have Signed Your Will And Special Needs Trust

Congratulations! You have taken a big step in protecting your family's future! Your wills and special needs trust will insure your loved one with a disability will be able to collect government benefits, i.e. Supplemental Security Income, Medicaid, SNAP, etc, and still have the benefit of their share of your estate, stocks, real estate holdings, 401K account, other retirement accounts, and any life insurance policy benefits.

The Steps Of What To Do After You Have Signed Your Will And Special Needs Trust

1

What To Do After Creating Your Special Needs Trust

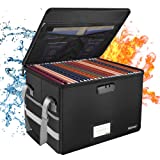
  • Fireproof File Box Store your Wills and Trust safely.
    Keep your original Wills and Special Needs Trust in a secure place in your home where you store important documents. An unlocked fireproof file is ideal — unlocked because your Personal Representative (Executor) must be able to access them to deliver to your lawyer or file with the court. (You can get one by clicking here.)
  • Inform key people where they are.
    Let your Personal Representative (Executor) and the Trustee of the Special Needs Trust know where the documents are stored and how they can access them.
  • Provide copies.
    Give both your Personal Representative (Executor) and the Trustee of the Special Needs Trust a copy of your Will and Special Needs Trust — either in paper or electronic form.
  • Update your beneficiaries.
    Change the beneficiaries of your retirement accounts, life insurance policies, or other brokerage accounts intended for your child with a disability to the Special Needs Trust.
  • Inform family members about the Trust.
    Let relatives — especially grandparents, aunts, and uncles — know that you have established a Special Needs Trust for your child.

    This is important to prevent them from accidentally leaving money directly to your child in their Will.

    Instead, they should direct gifts or inheritances to the Trustee under "The [Your Child's Name] Trust for the benefit of [Your Child's Name]."
  • 💡 If Grandma, Grandpa, or anyone else wants to make a gift during their lifetime:

    Tell them not to give money or assets directly to your child. Any gift should go to the Special Needs Trust, so it does not affect your child's SSI or Medicaid eligibility.

    For smaller gifts (under the annual gift limit), they might also consider contributing to your child's ABLE Account if one has been established.
  • Decide whether to fund the Trust now or later.
    Most people do not fund the Special Needs Trust immediately — instead, it is typically funded after your death using the assets you've designated in your Will or beneficiary designations (such as life insurance or retirement accounts).
  • Do not use your child's own funds.
    Never fund this trust with money or property that already belongs to your child with a disability. Those assets must go into a First-Party Special Needs Trust. (For more information, click here.)
  • Consider creating an ABLE Account.
    Depending on the amount of assets, an ABLE Account can be a helpful, flexible supplement to a Special Needs Trust.
  • Opening a bank account for the Trust.
    If you are funding the trust now, you will need a Tax ID Number (EIN) from the IRS. You can apply for one online (click here to go to the IRS website), or we can assist you with this process for a modest fee. Detailed instructions (click here)

    Once you have the EIN and a copy of the trust, bring both to your bank to open the account.
  • Have questions? We're here to help.
    If you have any questions about any of these steps, please contact us.

Need Information About Special Needs Trusts?

Our team is here to guide you every step of the way — with plain-English explanations, no legal jargon, and affordable expert support built for families like yours.

Visit Special Needs Trusts Online
Tom Sannicandro

About the Author — Tom Sannicandro

I am Tom Sannicandro, a Special Needs Trust Attorney and I am here to help. I am the founder of a nonprofit corporation that provides quality information about resources available to families as well as providing affordable Special Needs Trusts and estate planning for families. I have over 20 years of experience helping families just like yours. Find out more information at SpecialNeedsTrustsOnline.com or click here to set up a free appointment.

★ Exclusive Offer
10% OFF
All Services

Subscribe & Save on
Your Next Service


Subscribe to our newsletter and receive a 10% discount on all our services. Select your preferred service below and we'll send your personalised offer straight to your inbox. If you don't see it in your inbox, check your spam or contact us at tom@specialneedstrustsonline.com

This field is for validation purposes and should be left unchanged.

🔒 We respect your privacy. No spam, ever. Privacy Policy