Have Questions? Call Us For Help: 508-690-0012

What’s the Difference Between SSI and SSDI?

What Is the difference between SSI and SSDI?

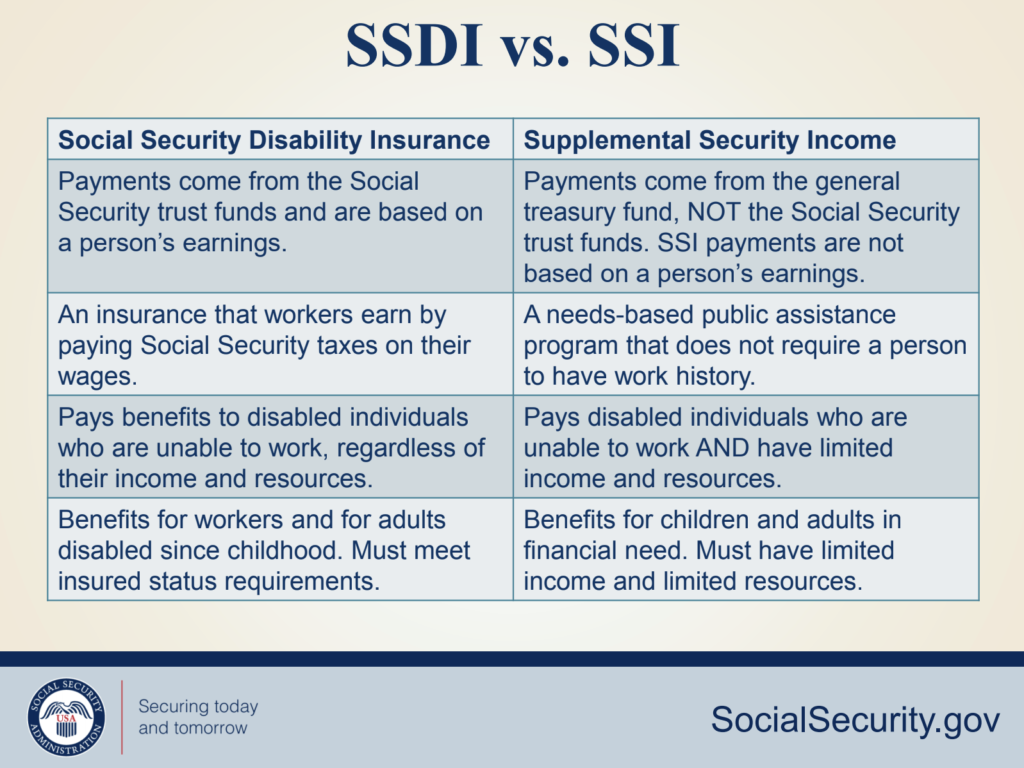
The major difference is that SSI determination is based on age/disability and limited income and resources, whereas SSDI determination is based on disability and work credits.

In addition, in most states, an SSI recipient will automatically qualify for health care coverage through Medicaid. A person with SSDI will automatically qualify for Medicare after 24 months of receiving disability payments (individuals with amyotrophic lateral sclerosis [ALS] are eligible for Medicare immediately).

How does Social Security define disability?

Social Security uses a strict definition of disability that relates to your ability to perform work and the projected length of your disability. It requires that you submit medical records to support your application. If you have a short-term or partial disability, you are not eligible for SSI or SSDI.

How do I apply for SSI or SSDI?

You can apply for SSI online only if you are an adult with a disability. SSI applications are not available online for people applying for a child under age 18 with a disability or a non-disabled senior aged 65+. These individuals must visit their local Social Security office or call 1-800-772-1213 (TTY 1-800-325-0778) between 7 a.m. – 7 p.m., Monday through Friday. You can apply for SSDI benefits online at any age. You also can apply by calling Social Security at the number above or at your local office.

How do I apply for SSI or SSDI?

The Supplemental Security Income (SSI) program provides monthly payments to adults and children with a disability or blindness who have income and resources below specific financial limits. SSI payments are also made to people age 65 and older without disabilities who meet the financial qualifications.

You may be eligible to receive SSI monthly payments even if you are already receiving Social Security Disability Insurance or retirement benefits.

Apply for SSI Online Now!

Other Ways to Apply

Apply By Phone

Call us to make an appointment to file your application at 1-800-772-1213. If you are deaf or hard of hearing, you can call us at TTY 1-800-325-0778.

Apply Online

  • Start a disability claim online (if age 18-64)
  • Start a child’s disability claim online (under age 18)

More about the program

SSI is a Federal program funded by general tax revenues (not Social Security taxes). It provides monthly payments to meet basic needs for food, clothing, and shelter. The base monthly federal amount varies depending on your living arrangement and countable income. Not everyone gets the same amount. You may get more if you live in a state that adds money to the federal SSI payment. You may get less if you have other income such as wages, pensions, or Social Security benefits. You may also get less if someone pays your household expenses or if you live with a spouse and he or she has income. You may be able to get SSI if your resources are worth $2,000 or less. A couple may be able to get SSI if they have resources worth $3,000 or less.
Anyone may apply for SSI. The SSI program provides monthly payments to people who: Are at least age 65 or blind or disabled. Have limited income (wages, pensions, etc.). Have limited resources (the things you own). Are U.S. citizens, nationals of the U.S., or some noncitizens. Reside in one of the 50 states, the District of Columbia, or the Northern Mariana Islands. Exception: The children of military parent(s) assigned to permanent duty outside the U.S. and certain students temporarily abroad may receive SSI payments outside the U.S.
Anyone who believes they meet Federal Disability requirements is eligible to apply. Your family members may also receive benefits if you can no longer work due to a medical condition. You are considered disabled under Social Security rules if: You cannot work due to a medical condition; You cannot do work that you did before; We decide that you cannot adjust to other work because of your medical condition(s); and Your disability has lasted or is expected to last for at least one year or to result in death. People who have worked long enough may also be able to receive Social Security Disability Insurance benefits as well as Supplemental Security Income (SSI) benefits.


Need Information About Special Needs Trusts?

I am Tom Sannicandro, a Special Needs Trust Attorney and I am here to help. I am the founder of a nonprofit corporation that provides quality information about resources available to families as well as providing affordable Special Needs Trusts and estate planning for families. I have over 20 years of experience helping families just like yours. Find out more information at SpecialNeedsTrustsOnline.com or click here to set up a free appointment.

When is a Special Needs Trust Needed?

Have You Wondered When Is A Special Needs Trust Needed?

A special needs trust is needed if your child with a disability is expected to be able to collect Supplemental Security Income, SSI, or some other government benefits, which could include Medicaid, SNAP, or housing benefits, when they become an adult. This would be because your child is unlikely to be able to support themselves by working independently. If you think this is a possibility, and you have assets you would like to leave your child when you die, you should have a Special Needs Trust.

A young girl in a wheelchair beams with joy as a group of medical staff applaud her in a hospital hallway, representing the supportive health care environment facilitated by a health care proxy.

What Is A Special Needs trust?

A special needs trust, also known as a “supplemental needs trust”, is an estate planning tool that enables a person with a disability or functional needs to receive financial support without negatively affecting any means-tested government benefits they’re receiving like Medicaid or Supplemental Security Income (SSI). Because needs-based government benefits have income and asset limits, receiving financial gifts or assets could reduce or eliminate eligibility. This means if you have an adult daughter with autism on SSI benefits and want to give her money to meet her living expenses, she could be disqualified from receiving needs-based government benefits. Likewise, if you die and leave her your Roth IRA worth hundreds of thousands of dollars or any amount that exceeds the asset limit, she could no longer receive SSI or Medicaid. But if you put the assets into a special needs trust for your daughter, she can keep her benefits and receive your financial support for the rest of her life. What can a special needs trust pay for? Money in a special needs trust is meant to be a supplemental resource, meaning it should cover expenses that aren’t already covered by government benefits. More specifically, the beneficiary should use the money for expenses other than food and shelter. You must ensure money is spent in accordance with IRS guidelines, so hold on to receipts or make a spreadsheet to keep track.

Benefits of a special needs trust

Setting up a special needs trust for someone can help you enhance their quality of life and give you peace of mind. These trusts ensure that a person with functional needs will receive the financial support they need throughout their lifetime, whether you’re here or not. Here are a few key benefits of special needs trusts: Your loved one can still receive needs-based government benefits. In some situations, creditors or lawsuit winners can’t access the funds or assets in the trust. Trust funds can be invested by a trustee or financial advisor. You may be able to have control over who inherits the trust when the beneficiary dies. Trusts provide protection against financial abuse, as trustees have a fiduciary duty to act in the beneficiary’s best interest.


Need Information About Special Needs Trusts?

I am Tom Sannicandro, a Special Needs Trust Attorney and I am here to help. I am the founder of a nonprofit corporation that provides quality information about resources available to families as well as providing affordable Special Needs Trusts and estate planning for families. I have over 20 years of experience helping families just like yours. Find out more information at SpecialNeedsTrustsOnline.com or click here to set up a free appointment

The Top 7 Reasons to Establish a Special Needs Trust

What is a special needs trust?

If you have a child or other loved one with special needs, you may want to establish a special needs trust. A special needs trust is an estate planning tool that can help you provide for the needs of an individual who is disabled without jeopardizing his or her eligibility for government benefits. A qualified attorney can help you establish and administer this type of trust.

reasons to establish a special needs trust

Reasons To Establish A Special Needs Trust

Unlike other types of trusts often used in estate planning, the primary goal of a special needs trust is to provide for the needs of an individual who is disabled throughout his or her life. Federal and state benefits are generally available to qualifying children and adults who have special needs. If your child qualifies for government benefits, one of your goals may be to help make sure that his or her eligibility continues into the future. A special needs trust can help you attain this goal. In addition, this type of trust can provide for supplementary care and services for your loved one.

To preserve eligibility for Medicaid

Medicaid, a joint federal-state program, provides medical assistance to those who are disabled and can demonstrate financial need. Children and adults can qualify for Medicaid only if their monthly income and the value of their other assets fall below certain limits, which vary from state to state. Most states set a $2,000 asset limit. In determining eligibility for Medicaid, a state may count only the income and assets that are legally available to the applicant. A special needs trust restricts the beneficiary’s own direct access to the assets in the trust to such an extent that the assets are not considered legally available to the beneficiary. Thus, a special needs trust can protect Medicaid eligibility because assets in the trust are uncountable.

To preserve eligibility for Supplemental Security Income (SSI)

Children and adults with special needs who have limited income and resources often receive monthly benefits from Supplemental Security Income (SSI). These cash benefits can be used for basic needs such as housing and food. But because SSI benefits are need-based, inheriting money can mean that a child with special needs will lose eligibility for this benefit program. By naming a special needs trust as your beneficiary instead of your child, however, assets can be devoted to the care of your loved one. In addition, since SSI recipients are normally automatically eligible for Medicaid benefits, preserving your child’s eligibility for SSI may preserve their eligibility for Medicaid as well.

To provide additional care and services

A special needs trust can be especially useful if you want to provide care and services necessary for your child’s well-being, without supplanting Medicaid benefits. Although Medicaid pays for a number of medical costs, including hospital bills, physician services, and long-term care, it will not subsidize items and services considered nonessential. These may include health-related expenses such as eyeglasses, dental care, rehabilitation services, and home health aide services, as well as personal expenses such as transportation, computer equipment, and vacations. To help confirm that trust assets are not considered legally available to the beneficiary, the trustee must have sole discretion over the distribution of trust income and principal. The beneficiary must have no control over the trust and no right to demand distributions from the trust. The trustee should purchase goods and services directly on the beneficiary’s behalf, instead of giving the beneficiary money from the trust to purchase items needed.

What requirements must a special needs trust meet?

If the trust is intended to supplement, rather than replace, government benefits, it must be properly drafted. Although requirements vary according to state law and the type of special needs trust established, here are some of the rules that apply to special needs trusts in general:

  • Generally, only a parent, grandparent, legal guardian, or court can set up a special needs trust. The person with disabilities, no matter how competent, cannot be the “creator” of the trust (even if the trust is funded by their personal assets).
  • Funds in the special needs trust may not be available to the beneficiary.
  • The beneficiary cannot revoke the trust.
  • The individual with special needs must be considered “permanently and totally disabled” under SSI criteria. Different rules apply to adults and children.
  • Under the terms of the trust, the trustee may not be permitted to make payments or distributions that might interfere with government benefit eligibility. Distributions cannot be made directly to the beneficiary.
  • Special needs trusts may be established as part of a will or during the creator’s lifetime.
  • Special needs trusts can hold an unlimited amount of funds and funds can be added at any time.

What types of special needs trusts are available?

Although there are many types of special needs trusts, they fall into two general categories: the third-party special needs trust, which is funded with assets belonging to someone other than the beneficiary; and the self-settled trust, which is funded with assets belonging to the beneficiary.

How is a special needs trust typically funded?

In many cases, a special needs trust is established, but not funded, while the parent or other creator is alive. Upon the parent’s death, their will transfers the child’s portion of an inheritance to the special needs trust. The trust (instead of the child) can also be designated as the beneficiary of various assets, such as employee benefits and life insurance policies.

Typically, a special needs trust is funded using:

  • Life insurance
  • Cash (including gifts from relatives)
  • Investments (e.g., stocks, bonds)
  • Retirement plan benefits (e.g., pension benefits, IRA funds, 401[k] assets)
  • Personal and real property
  • Proceeds from a personal injury settlement (applies to self-settled trusts)

What else should you consider for a special needs trust?

Selecting a trustee

A trustee is a person or institution selected to administer a trust and manage its assets. The trustee’s role is to adhere to the terms of the trust document and fulfill its objectives. You may wish to name yourself or another family member as trustee of the special needs trust, or you may wish to name a professional trustee. Another option is to name a family member and a professional trustee as co-trustees.

Providing a letter of intent

If you set up a special needs trust through your will, you might also want to draft a letter of intent to describe how you want your child to be cared for after you’re gone. Although it’s not a legal document, it can provide important information to guardians, trustees, family members, and others involved in the care of your child. The letter may address such issues as your child’s medical needs, daily routine, interests, likes and dislikes, religious practices, living arrangements, social activities, behavior management, and degree of self-sufficiency. Such a letter can prove invaluable to your child’s caregivers and can also make the transition to a new living situation as smooth as possible for your child.

Informing family members

Explain to siblings or other family members why you’re setting up the special needs trust. Although siblings might expect to receive equal inheritances, more resources will probably need to be set aside for the benefit of your child with special needs. Explanations and clear directions now may help avoid family conflicts later.

Setting Up a Special Needs Trust

I am Tom Sannicandro, a Special Needs Trust Attorney and I am here to help. I am the founder of a nonprofit corporation that provides quality information about resources available to families as well as providing affordable Special Needs Trusts and estate planning for families. I have over 20 years of experience helping families just like yours. Find out more information at SpecialNeedsTrustsOnline.com or click here to set up a free appointment.

Watch this video for an overview of special needs wills and trusts.

Below is the powerpoint with live links

Need Information About Special Needs Trusts?

I am Tom Sannicandro, a Special Needs Trust Attorney and I am here to help. I am the founder of a nonprofit corporation that provides quality information about resources available to families as well as providing affordable Special Needs Trusts and estate planning for families. I have over 20 years of experience helping families just like yours. Find out more information at SpecialNeedsTrustsOnline.com or click here to set up a free appointment.

Special Needs Trusts – What you need to know!

What You Need To Know About Special Needs Trusts

If you have questions about special needs trusts, set up a consultation. Your consultation is FREE. 

Source of Trust Assets

Based on their source of funding, Special Needs Trusts are categorized either as Third-Party Special Needs Trusts or First-Party Special Needs Trusts. Third-Party Special Needs Trusts are created and funded by someone other than the beneficiary, like a parent, grandparent or sibling. The trust will be established either during the lifetime of the creator or under the terms of the creator’s will. As explained below, a properly drafted Third-Party Special Needs Trust can provide for the special needs of a person with disabilities without jeopardizing his or her eligibility for government benefits. First-Party Special Needs Trusts are funded with a beneficiary’s own property, such as an inheritance or the proceeds from a lawsuit. Although the beneficiary’s own assets will fund the trust, the regulations governing First-Party Special Needs Trusts require that the beneficiary’s parents, legal guardian or the court establish the trust. Another requirement is that the beneficiary must not be over age 65 at the time the trust is funded. This type of First-Party trust is commonly referred to as an OBRA, or (d)(4)(A) trust, taking its name from the federal code section authorizing the trust. (OBRA stands for the Omnibus Budget Reconciliation Act of 1993, and the full statutory cite is 42 U.S.C. section 1396p(d)(4)(A).) In the case of a personal injury claim for the Beneficiary of a (d)(4)(A) Special Needs Trust, before the trust may be funded, most states’ Medicaid Programs must first be reimbursed for those benefits paid prior to the establishment of the Special Needs Trust for medical care necessitated by the wrongful acts that generated the recovery. This “pre-trust lien” may be satisfied only from that portion of the recovery that is specifically allocable to past medical expenses and costs. Transfers of a Beneficiary’s assets to a (d)(4)(A) Special Needs Trust are not penalized for purposes of means-tested benefits. Also, if the trust funds are smaller, the beneficiary may wish to instead create a pooled Special Needs Trust (a (d)(4)(C) trust), which does not prohibit the beneficiary from being the grantor and does impose an age limitation. With a pooled trust, the assets of many individuals are “pooled together” for investment purposes; however, the funds are allocated to each individual beneficiary.

Payback Requirements

A properly drafted trust agreement will address a trust’s obligation to reimburse governmental programs such as Medicaid, SSI or their state equivalent. With Third-Party Special Needs Trusts, the remainder beneficiaries will receive the entire balance of the trust because its assets are not subject to Medicaid payback provisions upon the death of the beneficiary. First-Party Special Needs Trusts are subject to payback provisions that provide Medicaid with a right to reimbursement from the property remaining in the trust upon the death of the beneficiary. If any balance remains after the Medicaid payback, the excess is then distributed to the designated remainder beneficiaries. If the First-Party Special Needs Trust is a pooled trust, in lieu of the Medicaid payback, remaining funds may instead be allowed to be donated to the pooled trust to be used for other beneficiaries of the trust. Per 42 USCA 1396P(d)(4)(C), qualifying pooled Special Needs Trusts include: A trust containing the assets of an individual who is disabled (as defined in section 1382c(a)(3) of this title) that meets the following conditions: (i) The trust is established and managed by a nonprofit association. (ii) A separate account is maintained for each beneficiary of the trust, but, for purposes of investment and management of funds, the trust pools these accounts. (iii) Accounts in the trust are established solely for the benefit of individuals who are disabled (as defined in section 1382c(a)(3) of this title) by the parent, grandparent, or legal guardian of such individuals, by such individuals, or by a court. (iv) To the extent that amounts remaining in the beneficiary’s account upon the death of the beneficiary are not retained by the trust, the trust pays to the State from such remaining amounts in the account an amount equal to the total amount of medical assistance paid on behalf of the beneficiary under the State plan under this subchapter.

Establishing Intent in the Trust Document

To avoid disqualification of a beneficiary for governmental support, applicable federal and state laws strongly suggest that the trust document make clear its intent that the trust assets will supplement, and not supplant or diminish, any governmental benefits to which the beneficiary may be entitled. The trust document should set forth clearly that the Special Needs Trust is not intended to be a basic support trust. Essential Items in Special Needs Trusts The following are essential characteristics of a Special Needs Trust: 1) It must be irrevocable; 2) It must be valid under federal and state local law; 3) It must negate a determination that trust assets are “available resources” of the beneficiary for purposes of Supplemental Security Income (SSI), Medicaid or an equivalent state program; 4) Many state programs also impose the requirement that in order to qualify as a (d)(4)(A) or (d)(4)(C) trust, the beneficiary must be disabled within the meaning of the rules governing Social Security Disability.

What Can the Trust Pay For?

Some sample trust distributions for the Beneficiary that should not affect his or her means-tested benefits, could include:

  • reasonable compensation of the Trustee, and allied professionals advising the Trustee, e.g. investment manager, attorney, fiduciary accountant
  • reasonable compensation of care providers, including family members, where appropriate (Medicaid is often resistant to paid family or friends of Beneficiary due to frequent abuses)
  • medical services and equipment not covered by government programs
  • domestic and personal care services (housekeeper, grooming, meal preparation)
  • household costs other than food, mortgage or rent, real property taxes, heating fuel, gas, electricity, water, sewer and garbage removal
  • pre-paid funeral and burial arrangements (however, if the Beneficiary dies before arrangements have been pre-paid, no payments for same may be made from the Special Needs Trust until after Medicaid pay-back is fully satisfied)
  • computer or augmentative communications devices, and internet service
  • television or other electronic equipment
  • apparel, including maintenance and repair of same
  • one vehicle used for transporting the Beneficiary (not including a purely recreational vehicle)
  • membership in recreational clubs, cultural institutions
  • professional services: attorneys, accountants, claims processors, advocates, coaches
  • academic or recreational courses or classes
  • home decor, furniture, furnishings, appliances
  • dry cleaning and laundry services and supplies
  • fitness equipment and club membership
  • auto maintenance and supplies
  • home security alarm and monitoring service
  • yard service and maintenance
  • insurance for home, auto, liability
  • linens, towels, bedding
  • personal care items and supplies
  • music lessons, cost of instruments
  • non-food groceries and sundries
  • educational needs and supplies
  • over-the-counter medications
  • pet, service animal and supplies, veterinary services
  • sporting goods and equipment
  • stationery, stamps
  • telephone service and equipment
  • therapies not covered by benefits programs
  • tickets to cultural or sporting events
  • transportation costs (bus, subway, paid driver)
  • cable TV
  • vacation for Beneficiary and one attendant
  • catch-all: “such uses and purposes as the Trustee deems appropriate under all circumstances” for the sole benefit of the Beneficiary

Choosing a Trustee

The selection of the trustee for a Special Needs Trust is an important aspect of special needs planning. Some of the characteristics of a trustee for a Special Needs Trust should include:

  1.  Experience to manage the assets pursuant to the prudent investor rules.
  2.  Where a pooled trust is involved a non-profit organization with trust powers must be the trustee.
  3.  Knowledge to exercise its discretion under the terms of the trust agreement to make payments on behalf of the beneficiary for supplemental, nonsupport disbursements.
  4.  The ability to avoid any conflict of interest that might occur if a family friend or family member were to act as trustee.
  5.  Skills to maintain clear and accurate financial records which, when necessary, can be used to prepare annual court accountings.
  6.  A trustee who will take a friendly and caring interest in the beneficiary.


Need Information About Special Needs Trusts?

I am Tom Sannicandro, a Special Needs Trust Attorney and I am here to help. I am the founder of a nonprofit corporation to that provides quality information about resources available to families as well as providing affordable Special Needs Trusts and estate planning for families. I have over 20 years of experience helping families just like yours. Find out more information at SpecialNeedsTrustsOnline.com or click here to set up a free appointment.

Why Should You Create a Special Needs Trust for Your Child?

Why should you create a special needs trust?

A special needs trust allows parents to set aside funds for medical expenses, education costs, and other things that would be difficult to pay for without one. The trust itself does not receive the money; instead, it distributes the money to the beneficiary.

The best thing about creating a SNT is that it allows parents to protect their children from being taken advantage of financially. If you create a trust before your child turns 18 years old, then you can ensure that his or her assets go directly to the person who cares for him or her. In addition, if you die while your child is still under age 18, then the trust will take effect after your death.

A SNT allows parents to set aside funds for their children’s future health care needs. The trust is funded by the parent(s), who then designate which medical professionals will be responsible for providing care. In addition, the parent(s) can specify what level of care should be provided. For example, if the parent wants to ensure that his or her child receives the best possible treatment, the parent might choose to fund a specialized facility. If the parent prefers to provide less expensive care, the parent could choose to fund a community hospital.

A Special Needs Trust allows parents to set aside funds for their children’s future care. The trust is usually funded with life insurance policies, annuities, bank accounts, stocks, bonds, real estate, and other investments. Parents can choose from several different types of SNTs, depending on what type of care their child requires. For example, if your child has a physical disability, such as cerebral palsy, then you might want to create a Living Trust. If your child has a mental health condition, such as autism, then you might consider creating a Health Care Proxy.

Special Needs Trusts Online Can Help!

I am a Special Needs Trust Attorney and I am here to help. I am the founder of a nonprofit corporation that provides quality affordable Special Needs Trusts to families. I have over 20 years of experience helping families just like yours. Find out more information at SpecialNeedsTrustsOnline.com or click here to set up a free appointment.

Massachusetts Special Needs Trust

The Importance of Special Needs Trusts In Massachusetts

What is a special needs trust?

A special needs trust is simply a legal document, an advantageous way to set aside money for a person with a disability.

The trust is intended to help preserve funds for a person with a disability, and enhance the person’s quality of life while protecting his or her eligibility for public benefits, such as Medicaid and Supplemental Security Income (also known as “SSI”).

A 1993 federal law permitted the creation of special needs trusts. The policies that must be followed in creating and administering them are detailed by the Social Security Administration.

Special Needs Trust Administration

Lifetime Security for Your Disabled Child Establishing a well-funded Special Needs Trust (SNT) for a child with a disability in Massachusetts is an important part of providing them with a lifetime of safety, security, and quality of life after you are gone. Money, managed well, means options, choices, and a better life.

How Can Special Needs Trust Funds Be Used?

Many trustees mistakenly believe that a Special Needs Trust can only be used to pay for medical goods and services or other items that are directly related to the beneficiary’s disability, however, if an SNT is well-drafted, that is not the case. Special Needs Trusts can be used to pay for just about anything that benefits the beneficiary, such as home and vehicle maintenance, vacations, computers, and other electronic equipment, education expenses, or monthly phone, cable, and internet services. It can be used to pay for things like rent, however, this reduces the amount of SSI benefit the beneficiary receives.

Precautions for SNT Trustees

It is important to note that there are technical requirements that must be met while serving as a trustee.

You must follow all of the terms and instructions in the trust document, even if they are more restrictive than public benefits law requires.

Trust assets for the beneficiary must be used in ways that do not affect the beneficiary’s public benefits.

Only beneficiaries of the trust may benefit. For a self-settled d4A Trust, that means just the disabled individual and for third-party SNTs, it means only those the trust document states may benefit.

The trust must be treated with the utmost respect. The trustee should not borrow from the trust nor commingle the trust assets with the trustee’s personal assets.

Administering a Special Needs Trust can be complicated and confusing, and making the wrong decision can be problematic. We are Special Needs Trust administration experts who provide trustees with the reliable advice they need to ensure the best quality of life for the trust’s beneficiary.

Plan for now & the future!


What Can SpecialNeedsTrustsOnline.com Do to Help?

Call Now: (508) 690-0012

Book an online appointment: Click Here

Services Provided

Special Needs Trusts Online Can Help!

I am a Special Needs Trust Attorney and I am here to help. I am the founder of a nonprofit 501(c)(3) corporation that provides quality affordable Special Needs Trusts to families. I have over 20 years of experience helping families just like yours. Find out more information at SpecialNeedsTrustsOnline.com or click here to set up a free appointment.

What is a Pooled Trust?

What is a Pooled Trust?

A pooled trust is an irrevocable supplemental needs trust (SNT) that, under Federal, Massachusetts, and many state statutes, allows people with disabilities and older adults seeking long-term care services to spend down excess funds in order to qualify financially or maintain eligibility for government benefits, such as Medicaid and/or Supplemental Security Income (SSI).

Pooled trusts give people with disabilities a way to access vital health benefits while utilizing the excess funds they deposit into the trust to pay for items and services not covered by those benefits.

In accordance with Federal statute, pooled trust accounts close upon the death of the beneficiary. Any funds that remain in the account must be retained by the trust or paid to the State(s) that provided Medicaid services on behalf of the beneficiary.

Who is eligible for a Pooled Trust?

Massachusetts and New York residents of any age who are disabled as defined by Social Security Law can establish a pooled trust to deposit excess monthly income and/or resources so that those funds are no longer considered when determining a person’s eligibility to receive services through means-tested government benefits.

Benefits of a Pooled Trust

Qualify and maintain eligibility for Medicaid and/or SSI benefits

Protect funds for supplemental needs that enhance the quality of life

Get care in the community and be able to afford to pay bills

Avoid having to spend-down funds quickly

How it Works?

Pooled trusts are established and managed by a not-for-profit organization, such as NYSARC, and a financial institution serves as a co-trustee. Each beneficiary has their own sub-trust account, however, the funds are pooled for investment and management purposes.

The Trustee will administer the account and distribute funds to pay third parties for eligible expenses and purchases that are for the primary benefit of the beneficiary when provided with required documentation. Once the funds are deposited into the trust, the money cannot go back to the beneficiary directly in order to protect their eligibility for benefits.

Trust funds can pay for many things, but not all requests can be paid in order to comply with the policies set by the Social Security Administration’s (SSA) program operations manual system (POMS).

If you have questions, give us a call at (508) 690-0012! Set up an appointment here and we would be happy to assist you.

An Overview Of A Pooled Trust

A pooled trust is a type of irrevocable trust that combines assets from multiple beneficiaries with disabilities for investment purposes. Managed by a nonprofit organization, the pooled trust allows individuals with disabilities to maintain eligibility for government benefits while still accessing funds for supplemental needs. Each beneficiary has a separate account within the trust, and funds are pooled together for investment management purposes, while distributions are made according to each beneficiary’s specific needs. Pooled trusts offer professional management and oversight, providing individuals with disabilities and their families a convenient and reliable option for managing financial resources while preserving eligibility for public benefits.

Special Needs Trust Massachusetts

What Is a Special Needs Trust?

A special needs trust, disability trust, or supplemental needs trust, is a legal arrangement and fiduciary relationship that allows a physically or mentally disabled or chronically ill person to receive income without reducing their eligibility for the public assistance disability benefits provided by Social Security , Supplemental Security Income, Medicare, or Medicaid. In a fiduciary relationship, a person or entity acts on behalf of another person or people to manage assets.

A special needs trust is a popular strategy for those who want to help someone in need without taking the risk that the person will lose their eligibility for programs that require their income or assets to remain below a certain limit.

How a Special Needs Trust Works

A special needs trust covers the percentage of a person’s financial needs that are not covered by public assistance payments. The assets held in the trust do not count for the purposes of qualifying for public assistance, as long as they are not used for certain food or shelter expenditures. Proceeds from this type of trust are commonly used for medical expenses, payments for caretakers, transportation costs, and other permitted expenses.

The party who creates the trust will designate a trustee who will have control over the trust. This trustee will also oversee its management and the disbursement of funds. Assets originally belonging to the disabled individual that get placed into the trust may be subject to Medicaid’s repayment rules, but assets provided by third parties such as parents are not.1 This type of trust is sometimes also called a “supplemental needs trust.” Special needs trusts are irrevocable neither creditors nor the winner of a lawsuit can access funds designated for the beneficiary.1

Source: investopedia.com


Setting up a Special Needs Trust Massachusetts or elsewhere in the US

Special Needs Trusts Online Can Help!

I am a Special Needs Trust Attorney and I am here to help. I am the founder of a nonprofit 501(c)(3) corporation that provides quality affordable Special Needs Trusts to families. I have over 20 years of experience helping families just like yours. You can set up your Special Needs Trust now online by clicking here. Find out more information at SpecialNeedsTrustsOnline.com or click here to set up a free appointment.

Lifetime Security for Your Disabled Child

Establishing a well-funded Special Needs Trust (SNT) for a child with a disability in Massachusetts or anywhere in the country is an important part of providing them with a lifetime of safety, security, and quality of life after you are gone. Money, managed well, means options, choices, and a better life.

Special Needs Trust Administration – How Can Special Needs Trust Funds Be Used?

Many trustees mistakenly believe that a Special Needs Trust can only be used to pay for medical goods and services or other items that are directly related to the beneficiary’s disability, however, if an SNT is well-drafted, that is not the case.

Special Needs Trusts can be used to pay for just about anything that benefits the beneficiary, such as: home and vehicle maintenance, vacations, computers, and other electronic equipment, education expenses, or monthly phone, cable, and internet services. It can be used to pay for things like rent, however, this reduces the amount of SSI benefit the beneficiary receives.

Can a special needs trust Massachusetts pay for a caregiver?

It is often necessary for a family to hire a caregiver to assist in providing care for a child, even an adult child, with disabilities. The special needs trust can pay for this care, but certain rules must be followed. There are a number of considerations when a trustee hires a caregiver for the beneficiary with disabilities. Certain rules pertain to whether the caregiver is a family member or not.

Insurance

One consideration is insurance. Whenever a trust employs a caregiver, whether it be a parent or another family member, or even a non-family member, insurance is an important consideration. Worker’s compensation insurance should always be considered where a caregiver is being employed. If the caregiver suffers an injury in the course of employment, the trust will be responsible. Worker’s compensation insurance makes sense. Casualty insurance is usually not an issue. However, where an outside non-family caregiver is employed, casualty losses from theft may result and appropriate insurance should be obtained.

Wage and Hour Laws

Wage and hour laws must be considered in setting payment for caregivers.

Withholding

There is an issue as to whether the caregiver is an employee or an independent contractor. If the caregiver is an employee, there must be withholding for FICA and FUTA. No such withholding is required for an independent contractor. The trust may consider employing a payroll service to administer payment to the caregiver. Caregivers often want to be paid “under the table.” It goes without saying that a trustee should always resist these requests. Significant factors in determining whether the caregiver is an employee or independent contractor include:

Instructions. Is the worker required to comply with the other person’s instructions with respect to when, where and how the work is to be performed?

Personal Service. Are the services to be performed personally or can they be sub-contracted?

Continuing Relationship. Is the relationship between the worker and the person being cared for continuing?

Work Hours. Is the worker required to work set hours?

Payment. Is the worker paid by the hour, week, or month?

Realization of Profit or Loss. Can the worker realize a profit or loss on an individual transaction?

Right to Discharge. Can the worker be discharged? If so, he or she is likely an employee.

Agency

It is almost always good practice for the trust to employ any non-family caregivers through an agency. It is a little more expensive to use an agency, rather than deal directly with a potential caregiver, but the agency has the responsibility of supervising the caregiver and paying taxes. The agency will be responsible for withholding and for worker’s compensation insurance.

Distributions to Parent as Caregiver

Most families prefer to keep their family members with disabilities at home and to keep the family intact. This is usually in the best interest of the special needs trust beneficiary. Family members are often in the best position to provide the care required by family members with disabilities. Many family member providers make significant sacrifices with respect to their careers and outside commitments. Providing care for the disabled family member becomes a life-long priority. Compensating the family caregiver from the self-settled special needs trust is often the only way that a family member is able to provide the necessary care. In many situations, the family caregiver must give up outside employment to provide this care. However, distributions from a special needs trust, especially a self-settled special needs trust, to a parent serving as a caregiver for a child with disabilities is fraught with problems. Trustees must carefully read the language of the trust document with respect to authorizing the trustee to make distributions for the beneficiary’s personal care needs. A properly drafted special needs trust should include language authorizing the trustee to retain the services of family caregivers. In the New York Region, which includes New Jersey, SSA is now taking the position that it is a violation of the sole benefit of the rule for a first-party special needs trust to pay a family member as a caregiver unless the family member is “medically trained.”

It should be noted that if a trust beneficiary is receiving only medical benefits under a Medicaid Waiver Program, these restrictions may not apply. For example, the Pennsylvania Department of Public Welfare (DPW) has indicated that it will not require training of family caregivers until the POMS are changed. Central Office did not indicate what is needed to document caregiver credentials. The Support Team suggested common sense be used and that the caregiver parent be trained appropriately. One factor that some State Medicaid Agencies consider is whether the parent left his/her job to care for the trust beneficiary.

Training

Is the proposed family caregiver trained to provide the services that are required by the person with disabilities? If not, the family member must receive training and even certification to perform these services. There are individuals available, usually, nurses, who will visit the family home and provide the necessary training. Since the trust cannot pay for this training, the parent usually makes payment out of the caregiver payments received by the parent.
Who Qualifies for a Special Needs Trust?

Who Can Benefit From a Special Needs Trust?

Consider making a special needs trust for a loved one who receives government benefits.

Someone With Permanent Special Needs

Special needs trusts are most commonly used for people who likely will need government assistance from the SSI and Medicaid programs their entire lives because of a permanent or severe disabling condition.

Not all persons with a disability qualify for SSI or Medicaid. Someone who is commonly understood to be “disabled” may not qualify for these public benefits if, despite the disabling condition, the person is able to earn a living.

People with blindness, developmental disabilities, Down syndrome, organic brain damage, chronic mental illness, physical paralysis (paraplegia), or congenital disabling afflictions such as cerebral palsy or cystic fibrosis have been the most common automatic beneficiaries of government benefits for persons with disabilities. But there are many other physical and mental conditions that meet the Social Security Administration’s definition of disability and that are likely to last a lifetime.

Source: nolo.com

Someone With Special Needs Who May Not Need Benefits Later

Many factors make it hard to predict whether someone who currently has a disability will always need to rely on SSI and Medicaid. Many disabling conditions are not permanent and changes in the workplace, new treatments for disabilities, and new technologies for living with disabilities may affect whether your loved one will need government benefits in the future.

While you may not be able to know with certainty whether your loved one will continue to need SSI or Medicaid, you can create a special needs trust without worrying that you will needlessly tie up your loved one’s inheritance. Most special needs trusts take into account the possibility that the trust, for whatever reason, may not always be necessary, and they give the trustee power to terminate the trust if that is the best for the beneficiary.

Source: nolo.com

Someone Who May Need Benefits Later

Some people who aren’t disabled now may need assistance from SSI or Medicaid at some point because of a condition that is likely to get worse. In this situation, creating a special needs trust involves some guesswork. But if you think it’s more likely than not that a loved one will need government assistance for a significant length of time, it makes sense to set up a special needs trust now. In the trust, you can give the trustee the power to terminate the trust if it is not needed.

Source: nolo.com

Someone Who Is Eligible for Medicare or SSDI

A loved one who receives Medicare or Social Security Disability Insurance (SSDI) may not need a special needs trust because these programs do not base eligibility on the amount of money or assets an applicant has. However, if the SSDI payment is low, SSI may be a valuable way to supplement your loved one’s income. And Medicaid may be necessary to provide benefits not included in the Medicare program for instance, long-term nursing home care.

Source: nolo.com

Someone Who Cannot Manage Finances

People whose temperaments make it unlikely that they will be able to wisely manage an inheritance are good candidates for a special needs trust, even if they ultimately won’t need SSI or Medicaid. Such trusts are often called “spendthrift” trusts when used to keep assets out of the hands of a beneficiary (and of his or her creditors) and in the firm control of a wise trustee. For example, someone with mild developmental disabilities, mild autism, attention deficit disorder, or bipolar syndrome might benefit from a trust that prevents reckless spending of inherited money even in the absence of a disability. (Read more about Spendthrift Trusts Another good reason to use a special needs trust is to prevent a loved one with a disability from being the victim of predators. There are many unscrupulous and dangerous people out there who will target a person with mental or physical disabilities if they believe the person has money. A special needs trust prevents a person with a disability from falling prey to these predators because the person with a disability does not have control over trust funds.

Talk to a Lawyer

Need a lawyer? Start here. 

Special Needs Trusts Online Can Help!

I am a Special Needs Trust Attorney and I am here to help. I am the founder of a nonprofit 501(c)(3) corporation that provides quality information about resources available to families as well as providing affordable Special Needs Trusts and estate planning for families. I have over 20 years of experience helping families just like yours. Find out more information at SpecialNeedsTrustsOnline.com or click here to set up a free appointment.
Source: specialneedstrustsonline.com

★ Exclusive Offer
10% OFF
All Services

Subscribe & Save on
Your Next Service


Subscribe to our newsletter and receive a 10% discount on all our services. Select your preferred service below and we'll send your personalised offer straight to your inbox. If you don't see it in your inbox, check your spam or contact us at tom@specialneedstrustsonline.com

This field is for validation purposes and should be left unchanged.

🔒 We respect your privacy. No spam, ever. Privacy Policy